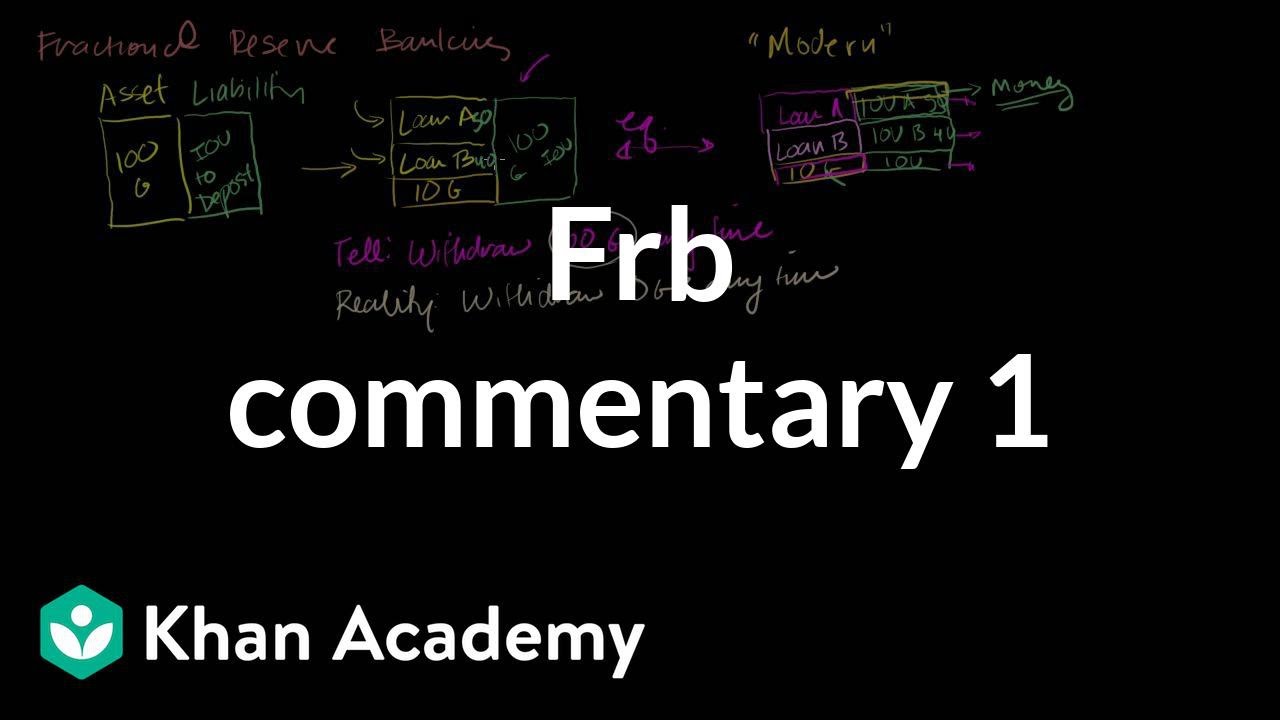
I” ve yapped concerning what
fractional reserve banking is, however I have kind of booked
making any kind of commentary on it, which” s what I ‘ m actually mosting likely to do in this video clip. Just as a little bit of an evaluation on the entire banking playlist, I started with a.
really simple instance of we” re on an island’. Allow ‘ s claim you had all of the. gold on an island and you give it to me for safekeeping. So now, I have this property called.
And I likewise have an obligation. This is my primitive island. If I were to draw your.
IOU to depositor.So at any type of point in time, I ‘ ve. You can come to me any time and take as much of.
your gold as you want. And we, naturally, recognize from the.
fractional get banking playlist that there ‘ s a small.
inconsistency between what I informed you, the depositor, and the.
fact of the circumstance, since the very first point that I
‘ m. mosting likely to do when you take this is, you recognize, I” ve taken. your deposits and I can bill you for
keeping your. money with me,’however I ‘ ve created a
a little sneakier. scheme, where I state, hey, I ‘ ve seen your behavior.You never take out even more than 10. gold pieces out at once. So what I do is I offer out all. 10 of your gold items. So we wind up with. the situation.
I have an IOU to you of 100 gold.
items like that, and I take the various other 90 gold pieces. and I offer
it out to random entrepreneurs on our island.
Car loan to A and that. is finance to B. And I believe this is fantastic,.
You obtain safekeeping, and I. collect the interest on it, and
perhaps that aids to fund.
making the safe good, and every person ‘ s happy.But plainly right here, there.
is a discrepancy. What did I tell you? What did I tell you,. the depositor? I told you that you can. withdraw 100 gold items at any type of time.
Currently, what is the truth? The truth is you can take out. 10 gold pieces at any type of time, and plainly, this is– I. don ‘
t recognize if you intend to call this a lie or otherwise,. yet this isn ‘ t totally true right here. And I know several of you may be.
claiming, hey, Sal, this is sort of a very primitive’instance.
of gold pieces, however our existing financial system. doesn ‘ t work rather like this.And simply to see to it that you.
I ‘ ll attract it right here.
This is the modern. banking system.
What you do is you provide me a. deposit of 10 gold items like that, therefore I say that,. yeah, sure, I owe you 10 gold items. So this is my IOU to you.
Every little thing looks nice and tidy. Now, however what I then do is after that I provide examining. down payments to other individuals, and my restriction on the amount of.
checking down payments I can release is based upon the book.
demands and all of that. Let” s state I have to keep. at the very least 10 %books, just maintain the mathematics simple. What I do in our contemporary.
system is I make a lending to B like that and I provided B a.
checking account that amounts your.
checking account. So this is an IOU to B.So this is basically a pledge.
to B that, look, this is an examining account, and.
at any time you can come and get this much. Perhaps this was 40, perhaps.
this is 50 gold pieces. This suggests that you can come.
at any kind of time and obtain 40 gold items from me. However we know the truth that.
people really don” t actually get the gold pieces. In our modern-day system, we ‘ re not. also dealing with gold.This will be reserve money,. It ‘ s the exact same idea that individuals are obtaining cash that. truly isn ‘ t always in the reserves. And, certainly, I ‘ m going to. make an additional financing to person A, and I ‘ m just going to. create a bank account down payment for them. I ‘ m simply mosting likely to develop an IOU. to A for 50, and the whole reason this
functions is because. people make use of these checking account deposits.
When I compose you a check,. I ‘ m simply transferring one of.
That ‘ s exactly how it works. I” ve told individuals, possibly’it
‘ s. just one person, that hey, you can come to me at any any type of and. Well, I ‘ ve told people that.
can take out 10. Right here, I ‘ m telling the depositor,.’you can take your cash whenever, where the. reality in this contemporary system is that
you can require. whenever– and I would throw an asterisk there– as long as. no more than 10% ask for the cash at the very same time. Now, clearly, I assume this. When, is– every person already comes to be a little awkward. you claim this, however you claim, look, this is what our modern. monetary system is based on and what this allows is this. person, this financial institution, nevertheless you intend to watch it, is permitted to.
be an intermediary in between the savers, the individuals who are.
giving their deposits, and individuals that require to invest the.
resources in developing new projects and whatever else. And the counterargument to that.
for somebody that” s versus fractional financial exists” s. absolutely nothing to quit you from doing this.All you need to
do is inform. this guy the truth.
What you do is, you do this.
You put on” t tell him you. You tell him you can take out 10.
gold items at any kind of time and that maybe an additional 40 gold.
items will certainly be readily available whenever this man is intended to.
repay his lending, maybe in a year, which the various other 50.
gold pieces would be available whenever this person pays.
his finance back. Maybe it” s in two years. So the inquiry is why. doesn ‘ t this take place? Well, the fact is due to the fact that if.
you told the depositor that they can” t have every one of their. cash as needed, he ‘ d say, OK, penalty. One, thinking that you ‘ re providing.
these individuals– these are legitimate individuals to provide your.
money to– I want several of the interest that you” re taking. because you ‘ re simply lending out my money. If you were to secure your.
The reality is they.
They can just get some. The next idea could be,.
OK, you” re being a little disingenuous when you inform the.
depositor that it” s on need and due to the fact that you” re being.
disingenuous, you” re allowed to kind of not give them as.
much passion as you would certainly have to provide if you told.
Doesn ‘ t the whole. And that might be true most of.
the moment, assuming everything I just informed you, but imagine.
a circumstance where we have numerous banks in.
This is financial institution one, I have financial institution. And bank one and bank.
And we all understand it” s very hard. They ‘ re excellent capitalists.
Bank 3 takes. on extra danger. Allow me create it’down. And what ‘ s their motivation. for taking added’risk? Let ‘ s claim that bank three is. happy to lend to people that banks one and 2 weren ‘ t. happy to provide to. So financial institution three ‘ s balance sheet.
right here, these car loans, are going to be riskier finances. Now why would certainly they do that? Since when you provide it to.
riskier people, you” re able to take even more passion from them. So they take added risk, which.
brings about extra rate of interest. And in fact, if you were to check out.
these banks, you would certainly state that this man” s the most.
profitable bank.Even worse, because he” s getting.
added passion, he can really share even more of that.
added interest with their depositors. You can provide higher yielding.
checking accounts, I guess I might call it. Higher interest on down payments. In this situation, the individual.
who” s taking the most run the risk of is going to be one of the most
. successful and they” re mosting likely to offer the higher passion.
which may in fact bring in the most down payments,.
? , if all these men look the very same.
.
quickly as points go negative? As quickly as the world obtains a.
bit of hard, this additional threat actually starts.
raising its hideous head and afterwards this person comes to be bankrupt. So this man” s– allow me
see if I. can draw his balance sheet. His equilibrium sheet will look.
He has a lot of loans out. He” s got some books. These are his car loans out.
As quickly as things begin going.
bad, several of these finances are going to go bad.As soon as one of those car loans. go bad, I” m mosting likely to become aware of it on the information,’and I ‘ m. going to run over to
the bank, and I ‘ m going to state, allow’me get.’my cash back as promptly as feasible. And let ‘ s state I ‘ m the. one there and I obtain my money back.
They promised it to me. I withdraw my account.
there, and I obtain all my cash back, and I basically.
diminish the books. Currently the following person ‘ s going. to find along.
This person was a little bit of. And the bank claims there. And after that this guy is mad.
And, certainly, during. this person ‘ s possessions are simply becoming worthless because he ‘ s. lent it to people that invested it terribly.
It ‘ s mosting likely to be illiquid. and bankrupt. And I ‘ ve explained the.
distinction, but’illiquid may indicate the loans could be great–.
and actually I ‘ ll reiterate it in this video– but the lendings. may be excellent, it simply doesn ‘ t have the cash. Financially troubled means that these lendings.
aren ‘ t good, that the worth of these car loans aren ‘ t. equal to these deposits. So I ‘ ll claim that this dangerous. financial institution is financially troubled.
Now, you may state these individuals. right below deserve it.
They individuals deserve what they got. since they were money grubbing. They invested in this high-risk.
financial institution that was doing shady points just to get a.
little greater rate of interest on their deposits. What happens when.
this occurs? Well, you have these good financial institutions.
over below that possibly did truly conventional borrowing. So this is what their equilibrium.
sheets– possibly both of their balance sheets appear like this. They have some reserves.
right there. They” ve made out some good fundings. to excellent entrepreneurs and after that you have their.
depositors. As soon as this person discovers.
out about what occurred at that financial institution, he” s like,
things.
are really bad.Let me simply be mindful and go.
to my financial institution– let” s claim it ‘ s this depositor right below– and. take my money out and put it into my cushion. So he goes to the financial institution
and. he ‘ s the initial one there. He ‘ s the fastest jogger of.
all of the depositors. He declares his down payment. His down payment, he.
withdraws, and he diminishes every one of the reserves. Currently, he wasn” t the only. individual that was afraid. This man was terrified too. So he comes going to the financial institution,.
and the bank now states, gee, I know I made this pledge.
to you that you have an on-demand account, however that.
man you saw leaving the financial institution with the running shoes on, he.
in fact just took every one of the reserves, and I presume I have.
to admit since I lied to you, that it isn” t totally.
on need. I actually loaned out the.
I was an excellent banker. These are in fact excellent loans.These lendings are still worth.
if you just wait long enough. you ‘ ll obtain your cash’back. And, certainly, this guy” s. going to be not so satisfied because he was lied to. And that” s not going. to be the only man. Somewhat slower joggers are.
going to come there and likewise require their cash. And this is known.
as a bank run. Because one possibly negative, where.
apple in the system actually is bankrupt, everybody ends up being.
afraid and states and comes, give me my money, and because.
we have this fractional book system, the.
It simply will not be there. And so once this takes place there,.
You” re going to have a run on financial institution two, and after that. everyone is mosting likely to take their cash out of the.
financial system.So the entire financial system,. this situation right here where the possessions maybe still. are worth the very same or more than the liabilities, this guy ‘ s. still solvent,’yet he doesn ‘ t have any money to’pay. these on-demand accounts, so this individual is encountering. a liquidity trouble. He doesn ‘ t have the gets’,. which ‘ s why we have the entire Federal Get that ‘ s. a lending institution of last resource.
This person can stroll to the Federal. Reserve and say, hey, I have some individuals knocking. on my door. Provide me some finances.
The Federal Get will provide. this individual some money, and, of training course, then this guy ‘ s going. to have an additional loan provider to it called the Federal Reserve and. he can utilize this to settle these individuals. However that leaves one more. concern: Exactly how does the Federal Get truly know the.
distinction in between this person– he could say, OK,.
this individual ‘ s excellent. Allow me simply lend to him to make. sure that he doesn ‘ t have a liquidity problem.How does the Federal Book.
truly know the distinction between this guy and this. person right below? This individual ‘ s mosting likely to also run. to the Federal Get.
Hey, Federal Book, these. financings are still great
. Just provide me a lending so I can pay. these individuals right there.
So the Federal Reserve claims,. hi there, you look excellent.
You ‘ re a wonderful clean banker in a. great, elegant structure wearing a Rolex on your arm. The Federal Get will certainly. Get some cash.
And I ‘ ll discuss what ‘ s been. crafted to repair this trouble:’basically. banking insurance.I ‘ ll most likely await that.
to the next video.
So this is the initial.
trouble right here. And then the second
problem is. that it actually ends up being tough to set apart between the. negative and good financial institutions. I suggest, it ‘ s not so difficult to. differentiate at face– well, it is hard to differentiate at. initially and comes to be even harder to distinguish when you. always have the Federal Get going to be a. lender of last resource. And when I speak about the.
Federal Reserve insurance policy, that makes it even harder to.
Since when times are excellent,.
a few of what has been crafted to fix these troubles.
and see if they really make good sense.
I ‘ ll draw it below.
And let ‘ s state I ‘ m the. Now, he wasn” t the only. And I ‘ ll talk concerning what ‘ s been. I mean, it ‘ s not so tough to.